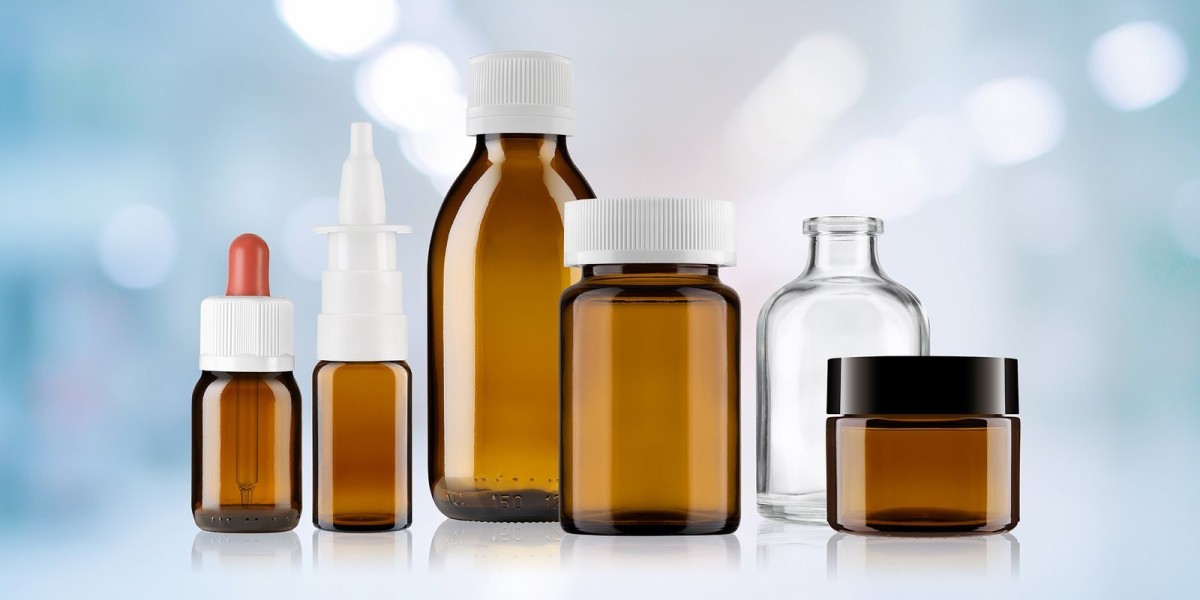

The Glass Packaging Market is influenced by a combination of consumer preferences, sustainability objectives, manufacturing economics, technological progress, regulatory developments, and demand from major end-use industries. Glass continues to hold an important position in beverages, food, pharmaceuticals, cosmetics, and personal care because of its chemical stability, barrier properties, transparency, recyclability, and premium appearance.
At the same time, the industry faces pressure from alternative packaging materials, energy-intensive production, transportation costs, and changing expectations around environmental performance. Understanding these forces is essential for manufacturers, packaging converters, brand owners, and other stakeholders planning long-term strategies.
Rising Demand for Sustainable Packaging
Sustainability has become one of the strongest influences on packaging decisions. Glass offers an important advantage because it can be recycled repeatedly without fundamentally changing its material properties. This supports circular packaging models and makes glass attractive to companies seeking to reduce dependence on virgin packaging materials.
Consumers are increasingly attentive to packaging waste and the environmental positioning of brands. This is encouraging companies to examine not only the appearance and functionality of containers but also their recovery, recycling, and reuse potential.
However, sustainability performance depends heavily on collection systems, recycling infrastructure, transportation distances, and manufacturing efficiency. Consequently, the environmental value of glass increasingly depends on how effectively the complete packaging cycle is managed.
Energy Costs and Manufacturing Economics
Glass manufacturing requires high-temperature furnaces, making energy consumption a major cost consideration. Fluctuations in electricity and fuel prices can therefore influence production costs, pricing strategies, and profit margins.
Manufacturers are responding through furnace modernization, improved heat recovery, greater automation, and increased use of recycled glass, commonly known as cullet. Higher cullet utilization can reduce the amount of energy required to melt raw materials while also lowering dependence on virgin inputs.
Energy efficiency is consequently becoming both a cost-management priority and an environmental strategy. Producers that can improve furnace efficiency while maintaining consistent glass quality may gain an advantage in competitive markets.
Lightweighting and Material Efficiency
Lightweighting is another significant factor shaping the industry. Traditional glass containers can be relatively heavy compared with certain plastic alternatives, creating challenges in transportation and handling.
Modern forming technologies allow manufacturers to produce thinner and lighter containers while maintaining the required strength and durability. Lightweight bottles and jars can reduce material consumption, transportation weight, and associated logistics costs.
The challenge is achieving the right balance. Excessive material reduction can increase the risk of breakage, particularly during filling, distribution, storage, and retail handling. As a result, successful lightweighting requires advanced engineering, precise forming processes, quality control, and performance testing.
Premiumization and Brand Differentiation
Glass packaging is strongly associated with quality, authenticity, and premium positioning. This makes it particularly valuable in alcoholic beverages, specialty foods, fragrances, cosmetics, sauces, gourmet products, and premium non-alcoholic beverages.
Distinctive bottle shapes, embossing, decorative finishes, colored glass, textured surfaces, and customized designs can help brands stand out on crowded retail shelves. Packaging is therefore becoming more than a protective container; it is increasingly part of the overall brand experience.
Premiumization can support demand for higher-value glass formats even when consumers remain price-conscious. Brands may accept higher packaging costs when distinctive glass designs contribute to perceived product quality and strengthen brand recognition.
Growth of Food and Beverage Applications
Food and beverage industries remain major demand centers for glass packaging. Bottles and jars are widely used for beverages, sauces, condiments, preserved foods, dairy products, jams, pickles, juices, and alcoholic drinks.
Glass provides strong protection against moisture, oxygen, and external contaminants. Its relatively inert nature also helps preserve product characteristics, which is particularly important for products where taste, aroma, and purity influence purchasing decisions.
Changing lifestyles are creating additional opportunities. Growth in ready-to-consume beverages, specialty foods, functional drinks, premium products, and convenience-oriented packaged foods can stimulate demand for appropriately sized glass containers.
Pharmaceutical and Healthcare Demand
Pharmaceutical applications represent another important influence on the Glass Packaging Market. Vials, ampoules, bottles, and other specialized containers are selected for applications where chemical stability, protection, and product integrity are essential.
The pharmaceutical sector often requires strict dimensional consistency, cleanliness, hydrolytic resistance, and compatibility with sensitive formulations. Consequently, glass manufacturers serving healthcare customers must maintain rigorous production and quality-control standards.
Growth in pharmaceutical manufacturing, injectable medicines, vaccines, diagnostics, and other healthcare products can create opportunities for specialized glass packaging. This segment can also encourage investment in higher-performance glass compositions and precision manufacturing technologies.
Regulatory and Environmental Pressure
Packaging regulations are increasingly influencing material selection. Governments and regulatory authorities are placing greater emphasis on waste reduction, recyclability, producer responsibility, recycled content, and circular-economy practices.
Such policies can encourage brands to reconsider packaging formats and improve collection and recovery systems. Glass can benefit from these developments because of its established recycling characteristics.
Nevertheless, compliance can also increase operational complexity. Producers may need to document material composition, recyclability, environmental performance, and supply-chain information. Regional differences in packaging rules can further complicate product design and market expansion for companies operating internationally.
Competition from Alternative Materials
The market does not operate independently of competing packaging materials. Plastic, metal, cartons, and flexible packaging can offer advantages such as lower weight, lower transportation costs, design flexibility, or reduced material consumption.
Plastic packaging, in particular, can be considerably lighter, which may provide logistical benefits. Metal can offer strength and durability, while flexible formats can reduce packaging volume.
Glass therefore needs to compete through a combination of performance, sustainability, aesthetics, safety, and product-preservation capabilities. Its strongest opportunities tend to occur where these attributes outweigh the disadvantages associated with weight and energy-intensive production.
Recycling Infrastructure and Cullet Availability
The availability and quality of recycled glass directly influence manufacturing efficiency. Clean, properly sorted cullet can be returned to furnaces and reduce the requirement for virgin raw materials.
Regional differences in collection infrastructure can therefore affect the competitiveness of glass producers. Strong deposit-return programs, effective municipal collection, sorting facilities, and established recycling networks can support a more reliable supply of cullet.
Contamination remains a challenge. Improperly sorted materials can compromise furnace performance or glass quality. Improving collection and sorting technologies is consequently an important factor in strengthening circular glass packaging systems.
Technological Innovation
Technology is transforming how glass containers are designed and manufactured. Advanced forming processes, automated inspection, digital quality monitoring, improved furnace technologies, and lightweighting techniques are helping producers improve productivity and product consistency.
Innovation is also expanding the design possibilities available to brands. More precise manufacturing can enable complex shapes, thinner walls, specialized closures, and differentiated surface treatments.
Future progress is likely to focus increasingly on reducing energy consumption, increasing recycled-glass utilization, improving production flexibility, and maintaining container performance while reducing material intensity.
Transportation and Supply Chain Considerations
Glass is heavier and more fragile than several competing packaging materials, making logistics an important market factor. Transportation expenses can become significant when containers travel long distances between manufacturers, filling facilities, warehouses, and retailers.
This encourages producers to establish manufacturing capacity closer to major consumption centers and filling operations. Localized supply chains can reduce transportation requirements while improving delivery reliability.
Supply-chain disruptions involving raw materials, fuel, machinery, or logistics can also affect production schedules. Companies with diversified sourcing and resilient distribution networks may be better positioned to manage such challenges.
Consumer Preferences and Changing Purchasing Behavior
Consumer attitudes increasingly influence packaging design. Some buyers associate glass with freshness, purity, premium quality, and authenticity. Transparency can also allow consumers to see the product before purchase, strengthening perceptions of quality.
At the same time, convenience remains important. Consumers may favor smaller formats, easy-to-handle containers, resealable designs, and packaging suitable for modern lifestyles.
These competing preferences are encouraging manufacturers to develop glass packaging that combines visual appeal with portability, functionality, durability, and environmental benefits.
Conclusion
The Glass Packaging Market Impacting Factors extend across sustainability, energy economics, technological innovation, consumer behavior, regulatory requirements, end-use demand, recycling infrastructure, and competition from alternative materials. No single factor determines market performance; instead, these influences interact throughout the packaging value chain.
The industry's future will depend on its ability to address the traditional disadvantages of glass while strengthening its core advantages. Lightweighting, higher recycled-glass utilization, efficient furnaces, advanced manufacturing, improved recovery systems, and innovative designs can help glass remain competitive.
As brands increasingly seek packaging that combines product protection, premium presentation, circularity, and regulatory compliance, glass is likely to remain an important packaging material. Companies that successfully integrate environmental performance with cost efficiency and functional innovation will be better positioned to capture emerging opportunities across food, beverages, pharmaceuticals, cosmetics, and other applications.






